
Navigating 2026 Charitable Tax Changes for Veteran Organizations
SEO ExcFederal charitable tax changes taking effect in 2026 are reshaping how donors, nonprofits, veteran charities, and philanthropic organizations approach charitable giving. New rules include a $1,000/$2,000 deduction for qualifying cash contributions by certain non-itemizers, a 0.5% AGI floor for itemized charitable deductions, and changes affecting the tax benefit of itemized deductions for high-income taxpayers. This policy guide examines the implications for veteran organizations, nonprofit fundraising, donor-advised funds, charitable giving strategies, and 2026 tax planning.
Strategic Policy Alert
From: Policy & Development Advisory Team, National Invest In Veterans Week® (NIVW)
To: Veteran Charities, Nonprofit Executive Leadership & Development Directors
Date: September 24, 2026
Subject: Technical Overview & Strategic Talking Points — 2026 Federal Charitable Tax Changes
Executive Overview
Federal legislation enacted through the One Big Beautiful Bill Act (OBBBA) changes the federal tax treatment of charitable contributions beginning with tax year 2026. These provisions affect both taxpayers who claim the standard deduction and taxpayers who itemize deductions. The changes generally apply to contributions made during 2026 and therefore affect federal returns filed in 2027.
For nonprofit and veteran-organization development teams, two changes are particularly significant:
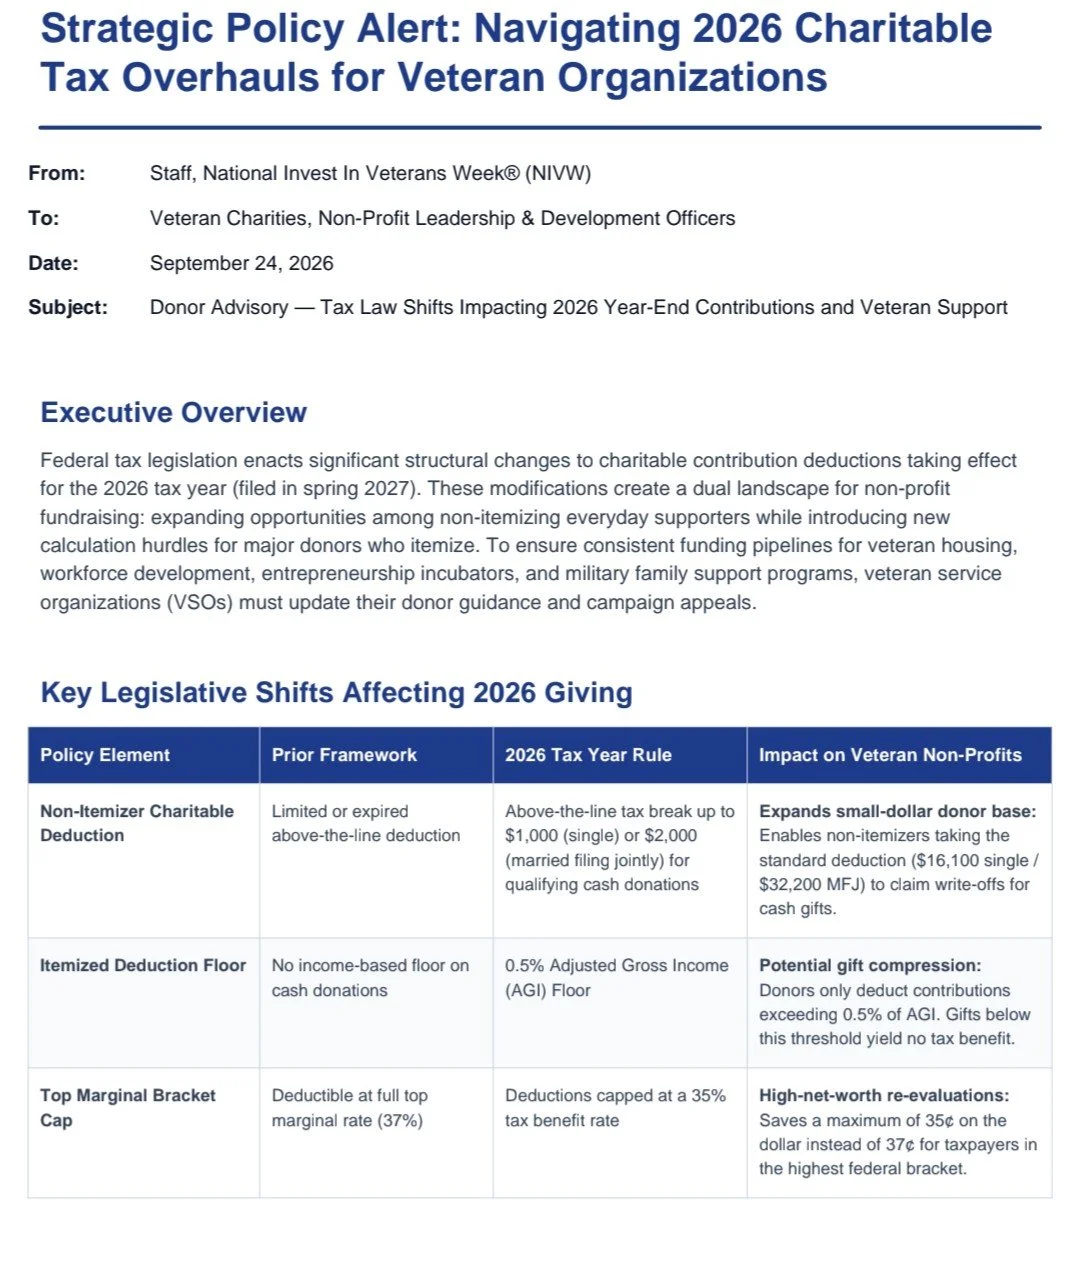
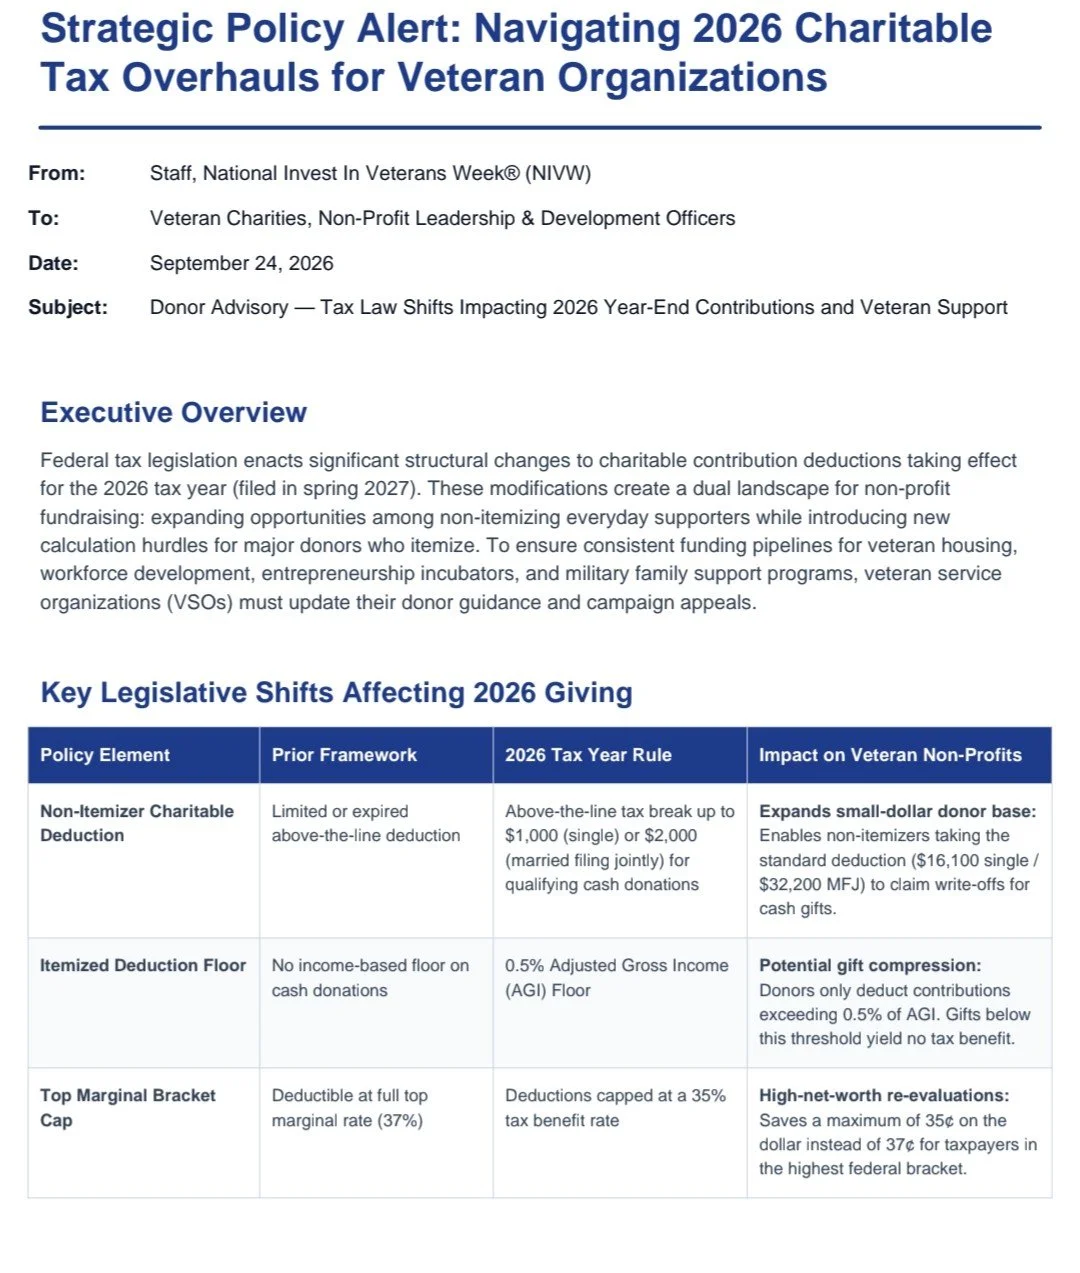
Non-itemizers: Beginning in 2026, eligible taxpayers who do not itemize may claim a federal deduction of up to $1,000 for individual filers or $2,000 for married couples filing jointly for qualifying cash contributions to eligible organizations.
Itemizers: Beginning in 2026, charitable contributions must exceed 0.5% of adjusted gross income (AGI) before the amount above that threshold becomes deductible.
The law also preserves the 37% top marginal individual income-tax rate while imposing a new limitation on the federal tax benefit of itemized deductions for taxpayers in the highest bracket. The IRS describes this as a limitation on the tax benefit from itemized deductions rather than a reduction of the underlying charitable contribution itself.
For veteran-serving nonprofits, these changes make accurate gift classification, donor communications, substantiation procedures and development-team training increasingly important.
Core Regulatory Changes
Regulatory Element 2025 Framework 2026 Federal Rule Operational Consideration Non-itemizer charitable deduction Generally unavailable for charitable contributions Up to $1,000 single / $2,000 married filing jointly for qualifying cash contributions to eligible organizations Donation systems and donor communications should accurately identify qualifying cash gifts. Itemized charitable deduction floor No 0.5% AGI charitable floor Contributions must exceed 0.5% of AGI before the excess is deductible Development teams should understand that smaller annual gifts may not produce the same itemized deduction as under prior law. Tax benefit limitation for highest-bracket taxpayers Itemized deductions generally received value based on applicable marginal rates, subject to existing rules OBBBA limits the tax benefit of itemized deductions for taxpayers in the highest marginal bracket Avoid describing this as a 35% "deduction cap"; it is a limitation on the tax benefit of itemized deductions. Standard deduction 2025 amount $16,100 single / $32,200 married filing jointly for 2026 The new non-itemizer charitable deduction operates alongside the standard deduction.
The IRS specifically identifies the $1,000/$2,000 non-itemizer deduction and the 0.5% AGI floor as OBBBA provisions effective for 2026.
The 2026 standard deduction amounts are $16,100 for single filers and $32,200 for married couples filing jointly.
Technical Example: Understanding the 0.5% AGI Floor
The new floor means that an itemizing taxpayer generally cannot deduct the first 0.5% of AGI in charitable contributions for 2026.
Example A — $400,000 AGI
AGI: $400,000
0.5% floor: $2,000
Charitable contribution: $10,000
Assuming the contribution is otherwise deductible and no other limitation applies:
$10,000 contribution − $2,000 floor = $8,000 potentially deductible amount
Example B — $500,000 AGI
AGI: $500,000
0.5% floor: $2,500
Charitable contribution: $10,000
Assuming the same conditions:
$10,000 contribution − $2,500 floor = $7,500 potentially deductible amount
These examples illustrate why a donor's AGI can affect the amount of a charitable contribution that produces a current-year itemized deduction. The IRS states that amounts falling below the 0.5% floor cannot be deducted for 2026.
Important: Actual federal tax results depend on the taxpayer's complete tax situation, including other deductions, contribution type, applicable percentage limitations and the rules governing the recipient organization.
Strategic Donor Communication
1. Grassroots & Mid-Level Supporters
Beginning in 2026, taxpayers who claim the standard deduction may be able to deduct up to $1,000 of qualifying cash contributions, or $2,000 for married taxpayers filing jointly, to certain eligible organizations.
Suggested donor-facing language
Beginning in 2026, federal tax law allows taxpayers who do not itemize deductions to claim a charitable deduction of up to $1,000 for qualifying cash contributions, or $2,000 for married couples filing jointly. Eligibility and limitations apply.
Organizations should avoid telling a donor that a particular contribution will produce a specific tax savings unless the donor's individual tax circumstances have been evaluated by a qualified tax professional.
2. Major Donors & High-Net-Worth Supporters
The 0.5% AGI floor means that itemizing donors should consider the interaction between their income, contribution amount, contribution type and other applicable deduction limitations.
Potential planning concept: concentrating contributions
Some donors may consider concentrating multiple years of planned charitable giving into a single tax year rather than making smaller contributions every year.
A Donor-Advised Fund (DAF) can be one vehicle used for this type of planning. However, donors should understand that a contribution to a DAF is not the same as a grant from the DAF to a nonprofit, and the new non-itemizer deduction has specific eligibility requirements.
Accordingly, nonprofit communications should describe "bunching" as a potential planning strategy, not as a guaranteed tax outcome.
3. Appreciated Securities
Donors considering gifts of appreciated long-term securities may wish to evaluate the federal tax consequences of contributing property rather than cash.
Depending on the circumstances, donating appreciated property to an eligible charitable organization can provide a charitable deduction based on the property's value while potentially avoiding recognition of capital gain that otherwise could arise from a sale.
However, special rules apply to noncash contributions, including substantiation requirements and percentage-of-AGI limitations.
Development officers should encourage donors to consult their own tax advisers before selecting an asset or contribution structure.
Development & Compliance Checklist
Gift Receipting
Maintain accurate records identifying the contribution date, amount and form of contribution.
Distinguish cash and noncash contributions in internal gift-processing systems.
Provide appropriate acknowledgments and substantiation documentation.
Do not characterize a donor's contribution as tax-deductible without confirming that the organization is eligible to receive deductible contributions.
The IRS advises taxpayers to maintain organized records and use the IRS Tax Exempt Organization Search tool to verify whether an organization qualifies to receive tax-deductible contributions.
Donor-Advised Funds
Clearly distinguish direct charitable contributions from DAF grants.
Do not represent a DAF contribution as qualifying for the special $1,000/$2,000 non-itemizer deduction.
Coordinate DAF communications with the organization's development and accounting teams.
Development-Team Training
Train gift officers on:
The 2026 0.5% AGI charitable floor.
The $1,000/$2,000 non-itemizer deduction.
Cash versus noncash contributions.
Appreciated-property considerations.
DAF mechanics.
Gift substantiation.
The distinction between a deduction and the donor's ultimate tax savings.
Implications for Veteran Organizations
The changes do not create a special federal charitable deduction exclusively for veteran organizations. Instead, veteran-serving organizations participate in the broader federal charitable-contribution framework when they meet the applicable requirements.
Accordingly, organizations should avoid messaging suggesting that Congress created a veteran-specific charitable tax incentive unless a particular provision expressly applies to veterans.
The opportunity for veteran organizations is operational: clearer donor education, accurate gift processing, stronger substantiation procedures and more sophisticated conversations with donors about contribution timing and form.
Important Tax Disclaimer
This advisory is provided for general educational and nonprofit-development purposes only. It is not tax, legal, accounting or investment advice and does not determine whether a particular contribution is deductible.
Tax treatment can vary according to filing status, AGI, contribution type, recipient organization, other deductions, applicable limitations and individual circumstances.
Donors should consult a qualified tax professional regarding their individual situation.
Authoritative Reference Sources
Internal Revenue Service (IRS): Statutory rules on charitable contribution reporting and substantiation under IRS Topic No. 506 (Charitable Contributions) and organization vetting via the IRS Tax Exempt Organization Search.
CNBC Personal Finance Coverage: Analytical framework from Why Trump's 'Big Beautiful Bill' May Shrink or Boost Your Charitable Tax Break for 2026, reported by Kate Dore, CFP®, EA (September 24, 2026).
Vanguard Charitable: Institutional research on the 0.5% floor and high-income deduction phaseouts via the Vanguard Charitable Tax Deductions Guide.
Fidelity Charitable / Viewpoints: Structural guidance on bunching strategies and multi-year giving accounts via Fidelity Viewpoints: Charitable Giving Tax Changes.
🫡Our Team
-
![A woman wearing a navy blazer with an embroidered coat of arms, gold lapel pin, and jewelry, sitting with her hands clasped, with American flags in the background.]()
President Angel Shuford
Chief Financial Officer (CFO) | Army Veteran
-
![A man in a blue suit and white shirt standing in front of an American flag against a black background.]()
Retired U.S. Army First Sergeant Kevin D. Shoun
Senior Advisor | Civic Leadership and Policy Development
-
![A woman with blonde hair smiling in front of an American flag and a black background with a logo that says 'National Invest in Veteran Owned Business Week.']()
Sara Pomposo
Chief Advisor | Audience Growth & Strategic Syndication
-
![A man in a red shirt holding a music award trophy, standing next to a framed platinum record plaque on display, with framed posters and awards hanging on the wall behind him.]()
Jim Freeman of The Five Satins
GRAMMY Hall of Famer | Brand Ambassador
-
![A man with gray hair and glasses stands behind a music stand, speaking into a microphone while using hand gestures, against a dark background.]()
Pastor Ron Henson
Social Impact Advisor | Navy Veteran
-
![A man in a U.S. military uniform in front of an American flag.]()
LTC Rickey L. Pope USA, Ret.
CO-FOUNDER | Retired Army Veteran, Retired Firefighter
-
![A man in a gray blazer and shirt posing with arms crossed in front of a city skyline at dusk, with buildings and a bridge reflected in the water.]()
Jeff Shuford
CO-FOUNDER | Iraq War Veteran & Military Spouse
-
![Three men in a discussion in an office break room with black and white geometric wallpaper. One man with a beard, wearing glasses and a suit, is talking to a bald man wearing a black sweater, who is making a gesture with his hands. The third man with dreadlocks, dressed in a blue suit and holding papers, listens attentively.]()
Drayton Florence
CO-FOUNDER | NFL Veteran & Military Brat
-
![A smiling man with glasses, wearing a green sweater over a striped collared shirt, standing with crossed arms in an office space near a window, with framed certificates on the wall behind him.]()
Erik M. Pelton & Associates, PLLC
Trademark Attorney | Veteran IP Advocate
-
![A man in a green vest with a plaid shirt and bow tie standing in front of a booth labeled 'Body Aqua' at a trade show or expo.]()
CPT Sherman WIlliams, USA, Ret.
Advisor | Retired Army Veteran
-
![Two men in business suits having a meeting in an office with a window showing a city view, discussing a presentation on a laptop.]()
Brandon Sugar
Legacy UX/UI Designer | Army Veteran
-
![A young man with dark hair styled back, light eyes, and a light beard, wearing a blue suit and white shirt, looking at the camera.]()
Mike Bicek
Creative Director | Army Veteran
-
![A small brown and black puppy sitting on a red folding chair at the beach, with sunglasses and a colorful bag in the background.]()
Private Jewel
Co-Founders Pup | Biewer Terrier
-
![A smiling man wearing sunglasses and a striped white shirt.]()
Lonnell McCall I
Sr. Spokesperson | Retired Navy Veteran
-
![]()
Celeste Everett
Legacy IT Consultant | Army Veteran
-
![Composite image of three young men dressed as a graduate, a football player, and a young man in formal wear against a stadium background.]()
Lonnell McCall II
Jr. Spokesperson | Military Brat
-
![Close-up of a young man with dark brown hair, styled back, with light eyes, a light beard, and wearing a dark shirt, standing in front of a background with horizontal lines.]()
Christopher B. Mueller
Lead Video Spokesperson | Veteran Advocate






“As an educator committed to professional growth, I fully endorse National Invest in Veterans Week® for recognizing that veterans are vital economic assets who deserve tangible support in entrepreneurship and workforce development.”